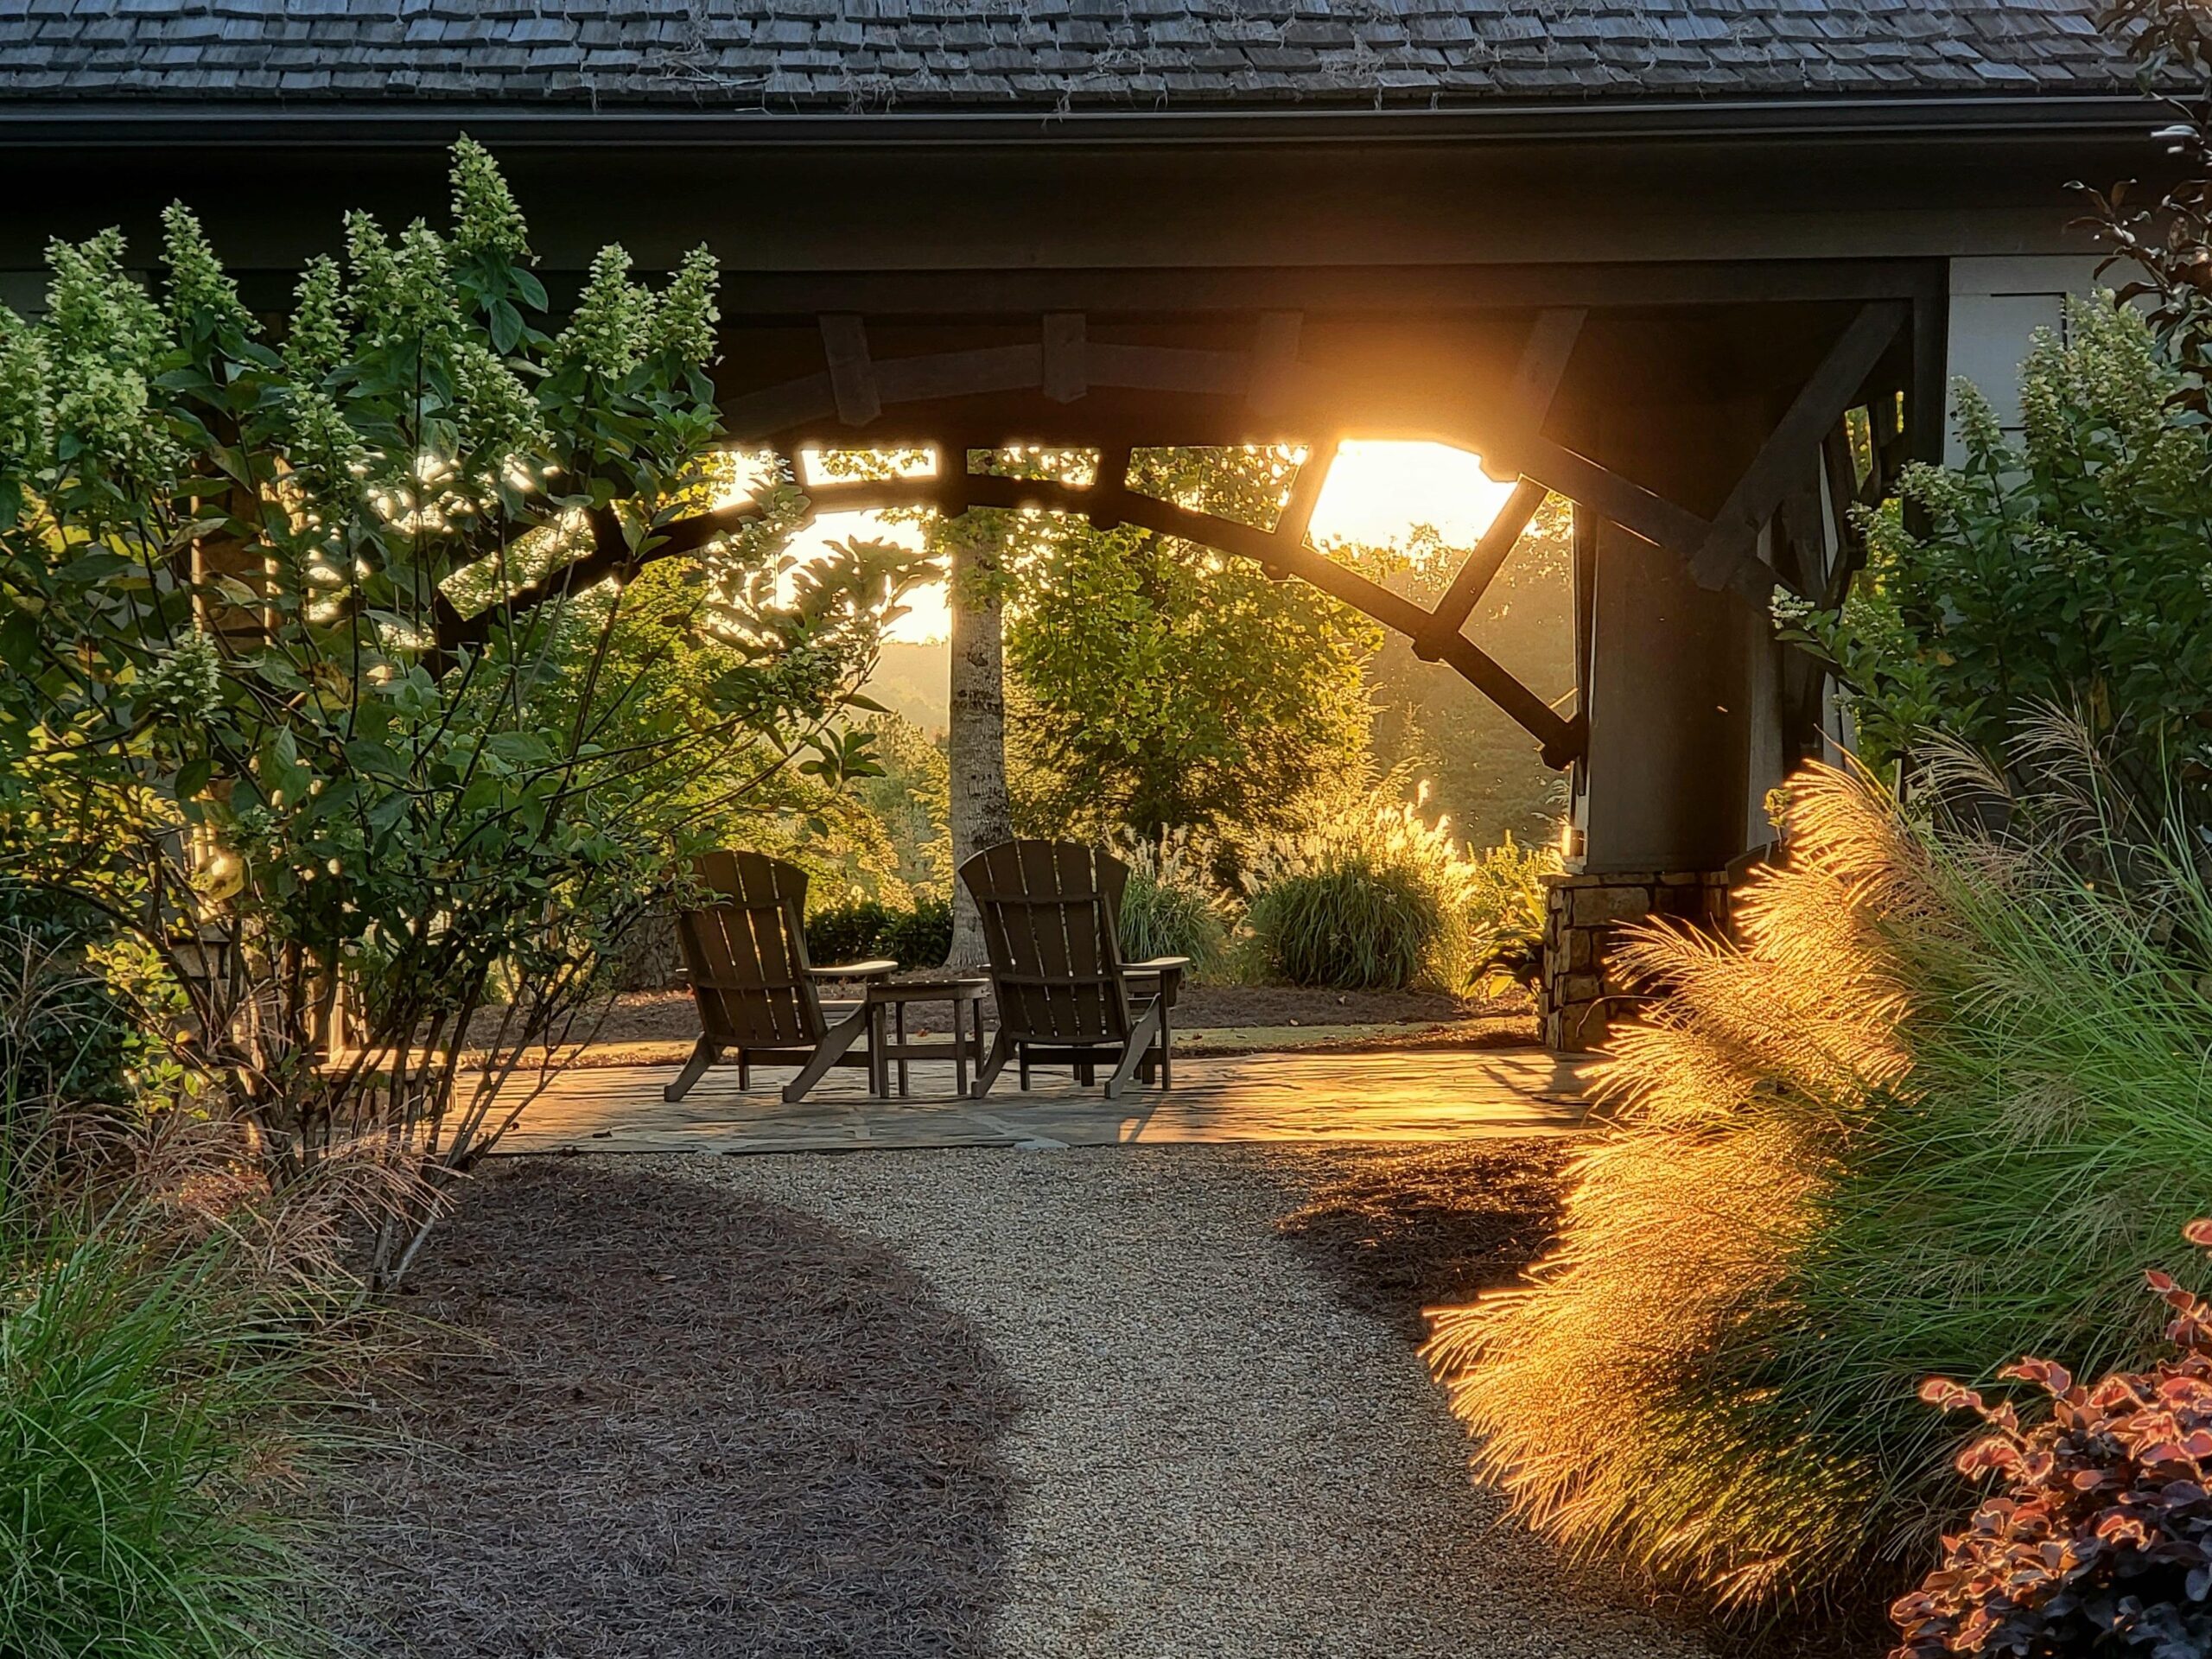
Enjoy the later days around Lake Keowee while you can, we are just 3 weeks away from “falling back”. That late afternoon of playing golf or enjoying many other outdoor activities will become harder. The good news is other Lake Keowee outdoor activities will become easier! Those that require cooler temperatures and have lighting available, like sitting by the firepit and playing a bit of tennis or racquet ball. The fall colors will be in full effect so, just imagine sitting by the fire will the sun drops below the horizon backlighting those fantastic shades of autumn!
No closings this past week though we do have three properties closing this coming week. We were also able to go on a couple of listing appointments that have led to a new listing that we expect to add next week. Be on the lookout!
These upcoming couple of months bring some of the most beautiful days of the year. Colors, crystal clear skies and crisp temperatures will be in play. There are still plenty of buyers in the market looking for the right Lake Keowee real estate. Yours could be the one, maybe now is the time to cash out? Now is one of the best times of the year to be on Lake Keowee!
Choosing the right mortgage will affect your very financial future. Here’s vital information to help you weigh your options and make a sound decision.
An Insider’s Guide to Understanding Mortgage Loans
Questions to ask while shopping for a loan
Before you can effectively compare mortgages, there are a number of questions you’ll need to ask the loan officer. Some are obvious, others are not. Be sure to ask them all.
Kinds of Financing – Fixed? Adjustable? What about government-backed programs? Any special deals you should be aware of? Make sure you’ve got a complete picture of the product menu.
Interest Rates – Rates differ not only between different types of loans. The same loan at three different lenders could have three different rates!
Terms – There are options beyond 15- and 30-year terms. Find out how different terms affect interest rates and how they impact the final cost of your home. This is especially important if you plan to be in the home for a long time.
Down Payment – What’s the minimum required for different loans? Today’s down payment can range from a high as the old standard 20 percent to nothing at all in certain targeted programs.
Loan Limits – Many lenders set limits based on a loan-to-value ratio. For example, with an 80 percent loan-to-value ration (LTV) you can only borrow $80,000 on a $100,000 home.
Loan Qualification – different lenders may qualify you using different formulas. Make sure you understand how you’re being evaluated.
Points – Think of these as prepaid interest charged by the lender. One point equals 1 percent of the face amount of your loan. In some cases points are paid up front; in others, they’re bundled into the loan. The latter saves you money up front but costs you more over the life of the loan. No-point loans also save you money up front, but lenders usually charge one-quarter to one -half point more than in the case of loans with points. Be sure to look at what your total cost will be over the life of the loan.